
The lessor's buyout quote starts from the residual it booked. The lessee needs the market's number.
An equipment lease with a fair market value purchase option ends with a choice: buy, return, or renew. The lessor sends a buyout figure, and the lessee usually has nothing to check it against. This guide covers when a buyout warrants an independent appraisal, how fair market value is developed for it, and where the asset's fair value can also matter under ASC 842.
On an FMV purchase option, the lessor's quote reflects the residual it set when the lease was written and the return it priced into the deal. An independent appraisal tells the lessee what the equipment would bring between a willing buyer and a willing seller on the buyout date. That gives the lessee a number to negotiate from.
Residuals are set years before the buyout, from assumptions about a used market nobody could see yet. By lease end, that market has moved one way or the other.
The quote and the market are two different numbers.
The lessor's quoted buyout reflects the residual it carried on its books and the return it priced into the lease. Depending on how the used market moved over the term, that figure can land well above what the equipment would bring in an arm's-length sale, and occasionally below it.
The lessee carries the exposure. Pay too much on the buyout and owning the asset costs more than buying comparable used equipment outright. Walk away from a fair buyout and the operation replaces equipment it could have kept for less. An appraisal effective on the buyout date shows which case you are in.
The asset's fair value is also an accounting input.
Under ASC 842, a lessee classifies each lease as finance or operating, and one of the tests compares the present value of the lease payments to the fair value of the underlying asset. Classification happens when the lease begins or is modified, using fair value as of that date.
If the buyout is handled as a modification or a new lease, the appraisal can supply the fair value input as of that date and give the controller and the auditor a documented source for it. The classification and the measurement remain the accounting team's call.
A buyout number you can put in front of the lessor.
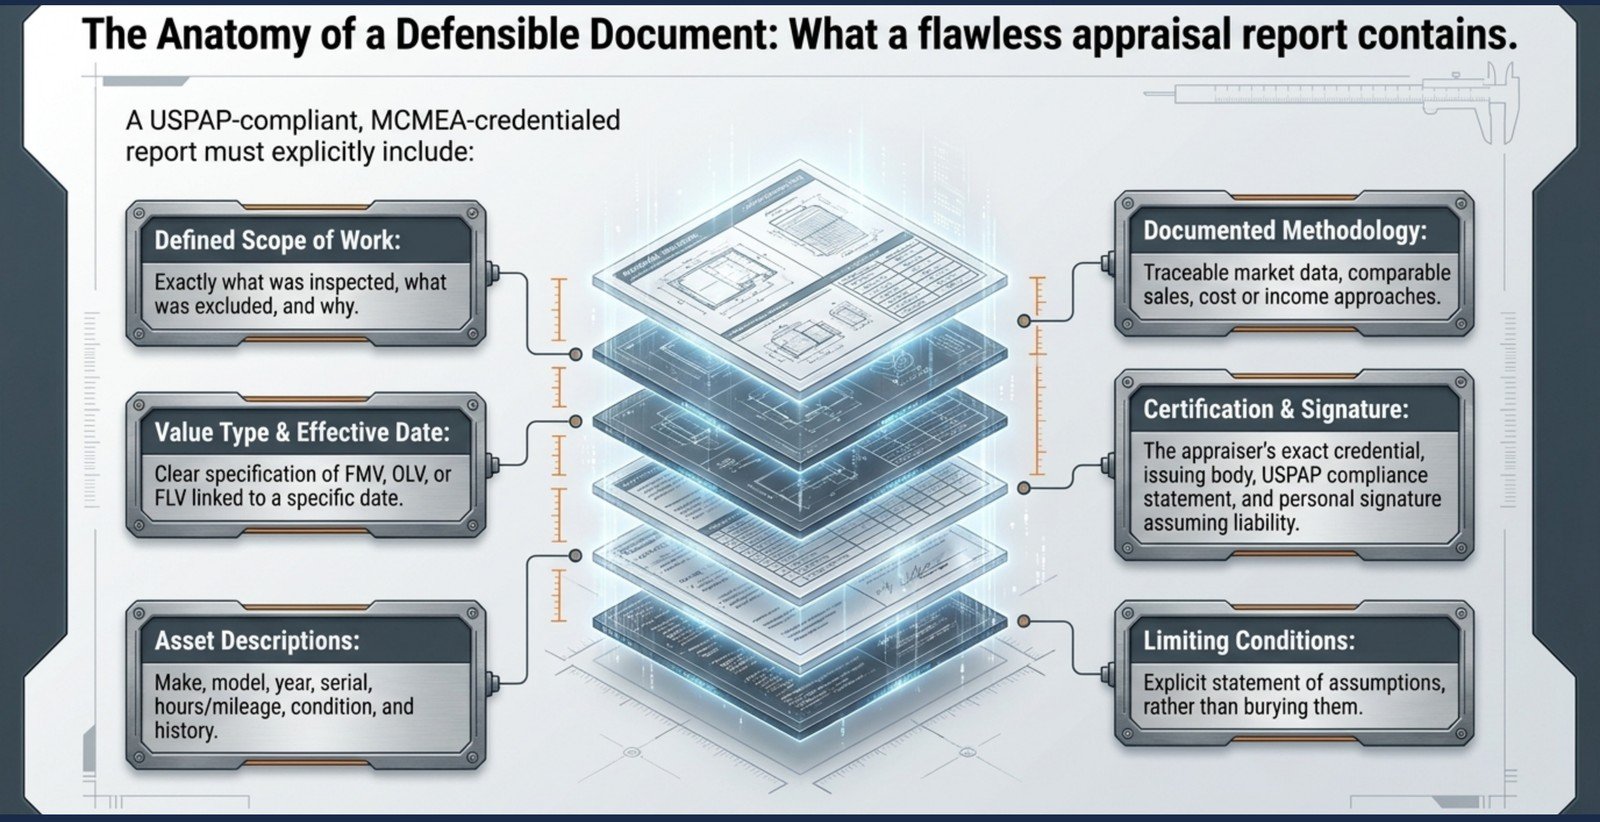
A buyout appraisal identifies each unit by make, model, serial number, hours, and condition, states fair market value with the buyout date as the effective date, and shows the comparable sales behind the conclusion. That is what lets a lessee answer a quote with evidence.
Residuals track the used market. Depreciation schedules don't.
What a leased excavator, press, or CNC machine is worth at lease end depends on hours, condition, configuration, and how many similar units are trading. A straight-line schedule can't see any of that. Comparable sales can.
Nathan Bazzle is one of 26 Master Certified Machinery & Equipment Appraisers in the United States.
Lease buyout appraisals, straight answers.
-
What is an FMV lease buyout?
An end-of-lease option to purchase the equipment at its fair market value instead of a fixed price. The lessee needs to know that value to decide whether buying, returning, or renewing makes sense.
-
Is the lessor's quote an appraisal?
No. It reflects the residual the lessor booked and the return it priced in. An appraisal is an independent opinion of market value developed to a stated standard.
-
Where does ASC 842 come in?
Lease classification compares the present value of the lease payments to the fair value of the underlying asset, measured when the lease begins or is modified. If a buyout changes the lease, the appraisal can supply that fair value.
-
Can a buyout be appraised mid-term?
Yes. The appraisal can be scoped whenever the buyout decision is live, mid-term or at expiration, with the effective date set to the buyout date.
-
Who orders it?
Usually the lessee. A lessor or a lender may also commission one. The opinion is independent of all of them.
-
Is this accounting advice?
No. The accounting and tax treatment stay with your team. The appraisal supplies the value they apply.
Check the buyout against the market before you sign.
Fifteen minutes to scope it: the equipment, the lease and its purchase option, the buyout date, and whether lease accounting is in play. You get an independent fair market value to negotiate and report against.
USPAP-compliant · MCMEA-credentialed · One of 26 in the U.S.